Lula’s Win: We Got It Wrong, but Less Wrong Than Prediction Markets, and Why That Matters
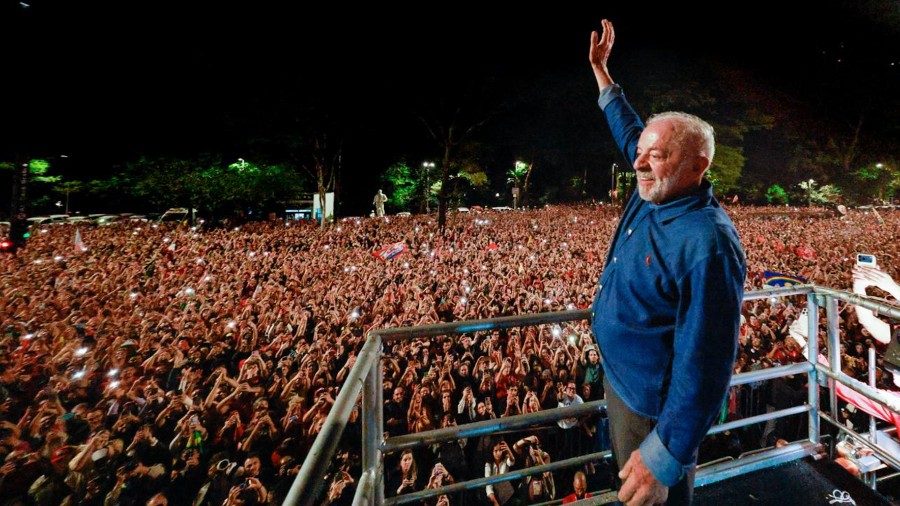
Lula won a fourth term on October 25, an outcome the model did not call. On election day it still favored Flávio Bolsonaro and gave Lula just 32%. But that sat well above the prediction markets, where Polymarket had Lula at 19%.
We flagged the gap early. In late September we put Bolsonaro at 45% while Polymarket had him at 58%, and that roughly 13-point edge in Lula’s favor held all the way to election day. The model tracked the race closer to the eventual result than the market, even while getting the final call wrong.
We want to be transparent with our forecasts, and they are publicly available here on VICO News. The model missed this one, but it was closer to the result than prediction markets were, giving Lula a better chance (32% on election day versus the market’s 19%). It picked up on something the market was missing, and getting closer to the real result is exactly what probabilistic forecasting is about.
That odds gap is where the money is: a fund trusting the model’s 32% over the market’s 19% could have hedged more Brazilian exposure against a Lula win, reducing losses when he pulled off the upset. In finance, being better calibrated than the market can save large sums of money even when the forecast is on the wrong side of 50%.
In our September 28th story, the VICO model argued a Bolsonaro win would be a good result for markets. Markets were priced for a Bolsonaro win, so Lula’s upset triggered a collapse.
The specific trades bear it out: Lula’s win knocked the real down about 12% against the dollar and sent the Ibovespa down over 13% in a day, tripping a circuit breaker, with stock futures off nearly 15% and the EWZ ETF falling around 5%. A fund long the real, Brazilian equities, or local bonds could have bought protection at the market’s 19% that the model’s 32% flagged as underpriced.